
Thank you for subscribing to my posts. If you’re not yet a paying subscriber, please consider becoming one. That’ll allow you to DM me with questions and comments. I plan to move my posts behind a paywall in coming months. Subscribing now locks you in at a low rate. Thank you so much for your support and feedback!
So many things about the Euro drive me nuts. There’s the fact that the ECB has been completely co-opted by high-debt countries - capping their government bond yields when the going gets tough like in the summer of 2022 - but then senior ECB officials have the nerve to give speeches on how it’s important to hold the line against fiscal dominance and moral hazard. Then there’s the fact that the EU is unable - even after four years - to mount a coherent response to Russia’s invasion of Ukraine. A recent example is the maritime services ban in the 20th sanctions package, which would have prohibited Western vessels from transporting Russian oil. This was undermined by the governments of Greece, Cyprus and Malta who are beholden to their shipping oligarchs. It’ll never happen. The madness of ongoing transshipments to Russia falls in the same bucket. And, finally, there’s complete paralysis in Germany’s political center on how to counter the rise of the AfD, which could end the Euro.
When I think about all this stuff, it seems blindingly obvious - to me - that the Euro should be much lower. But here’s the thing: markets don’t trade any of this stuff as it’s too amorphous and medium term. They’ll only price these things - which means drive Euro down a lot - when they get really obvious. That could be a court ruling banning ECB yield caps. It could be Putin testing NATO’s Eastern flank with an attack on the Baltics. Or it could be AfD leading Germany’s next government.
So - in today’s post on the Euro - I’m going to ignore all this and focus only on what markets are trading right now. We’re in a beggar-thy-neighbor world where the US and China are successfully muscling their currencies down. This means the single currency has to appreciate by default, so Euro overvaluation is going to get worse before it gets better. Nothing about this is good. It reminds me of the first few years after the 2008 crisis, when the ECB started hiking and the Euro rose sharply against the Dollar. Then came the sovereign debt crisis and it all fell apart. The current situation feels similar, it’s just that we haven’t reached the blowing up part yet.
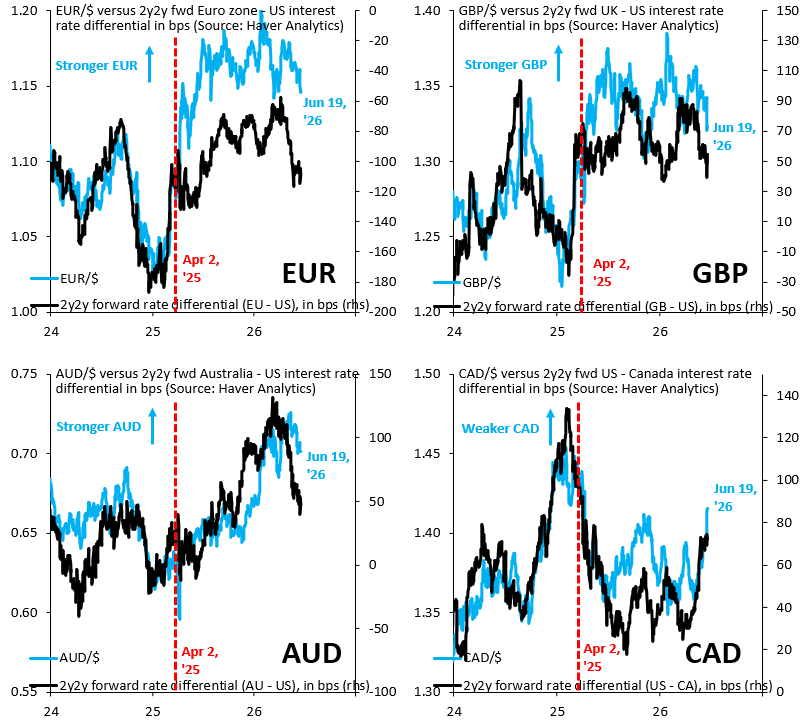
The blue line in the top left chart above is EUR/$. The black line is the differential of 2y2y forward interest rates in the Euro zone versus the US. I like using 2y2y forward rates because they’re a proxy for where terminal rates will be in any hiking or easing cycle. The striking thing about this chart is that EUR/$ moved very closely with the rate differential in all of 2024 and in early 2025, but then decoupled after the rollout of reciprocal tariffs on April 2. EUR/$ has been trading at a premium relative to the 2y2y forward differential ever since. The top right chart looks at whether there’s a similar decoupling for GBP/$. There is, but it’s much less noticeable. There’s no decoupling of this sort for AUD/$ in the bottom left chart and also nothing comparable going on for $/CAD in the bottom right chart. So the Euro got a unique lift from “Liberation Day.”
One way to interpret the decoupling between EUR/$ and the 2y2y forward differential is to say that EUR/$ needs to fall. I don’t think that’s right in this situation. “Liberation Day” gave EUR/$ a lift because markets added a risk premium for chaotic US policy to their Dollar outlook. The underlying driver of this decoupling is therefore the policy chaos in the US, which looks like it’ll continue until this administration ends. That means the decoupling will likely grow and EUR/$ will keep trending higher, which will make its overvaluation worse. That’s consistent with my view that we’ll see more Dollar weakness in the remainder of 2026.
what about: Eurozone's +2% current account surplus vs US' -3% (both % of GDP).
Always wrong you said all the things you say now in 2022.