
Thank you for subscribing to my posts. If you’re not yet a paying supporter, please consider becoming one. That’ll allow you to DM me with questions and comments. Your contribution will help cover the cost of the data I use in my posts, which I fund out of my own pocket. Thanks so much for your support and feedback!
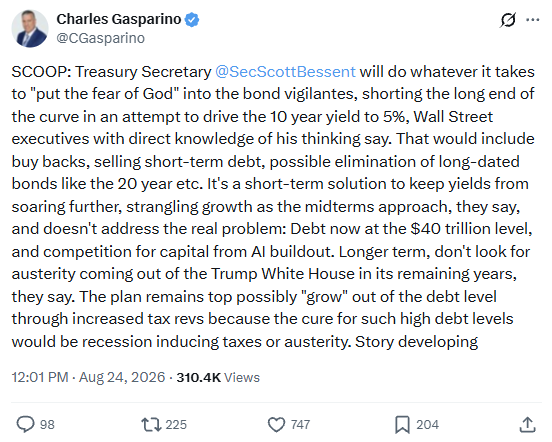
Headlines are coming fast and furious on potential plans by the US Treasury to keep long-term yields from rising. One such story - by Steve Liesman at CNBC - popped up yesterday saying that the Treasury General Account (TGA) may be used for buybacks. That’s a twist from last week’s announcement, where the presumption had been that buybacks of longer-dated debt would be financed by issuing short-term debt. This is different because it would involve outright purchases of bonds and a commensurate injection of liquidity into the economy. Another story is the tweet below by Charles Gasparino of Fox news, claiming Treasury will put the “fear of God” into bond market vigilantes who’re trying to drive the 10-year yield higher.
There’s a lot going on with all these headlines, so let me break things down into a few bite-size chunks for easier consumption.
These stories amount to verbal intervention. No official announcement was made yesterday by Treasury regarding US debt management, so these stories - at this point - amount to “verbal intervention,” i.e. they’re an attempt to scare markets from driving long-term yields up. Over the weekend, I did a post and a live stream on games high-debt countries play as they run out of fiscal space, including trying to scare markets and calling them irrational. In my opinion, this is almost always counterproductive because it showcases a vulnerability. Once you start drawing lines in the sand with markets, they’re invariably going to test you. So this all but guarantees that long-term yields will resume their rise.
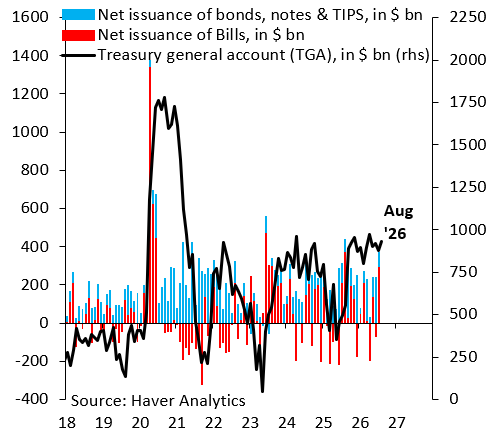
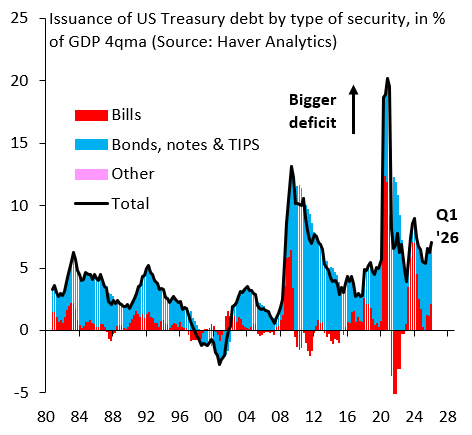
All this is tilting at windmills: as the black line above shows, the TGA currently stands around $1 trillion. If the government prefunds itself, i.e. issues lots of debt ahead of any actual spending as during the early stages of COVID, the TGA will rise and that cash can then be run down, including by buying back outstanding debt. All this is very well and good, but it misses the point. The TGA is finite, so it’ll only go so far. The ever-expanding deficit means debt issuance is continually growing, as the chart below shows, so using the TGA is confronting a “flow” problem with a “stock” measure. That never works. Flows always win that fight.
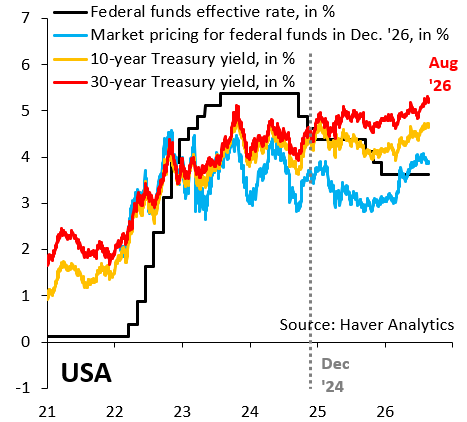
The vigilantes are unimpressed. The chart below shows the US yield curve. The black line is the midpoint of the Fed’s 25 basis point target range for the policy rate. The blue line is what markets price for this rate by the end of the year. The orange line is the 10-year Treasury yield, while the red line is the 30-year yield. Since last Wednesday’s buyback announcement, 10-year is down one basis point and 30-year is down six basis points, i.e. the impact on long-term yields is tiny.
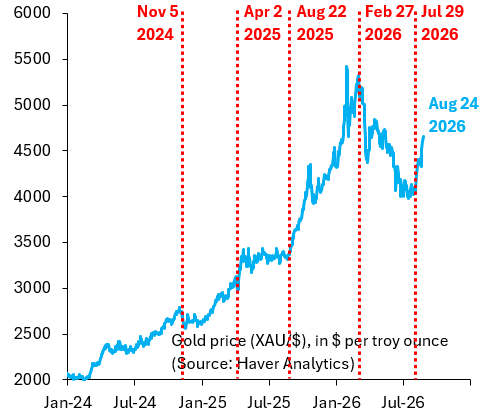
The debasement trade is loving this. The more high-debt countries blunder into artificial yield caps, which is where the US is heading, the more markets seek safe havens from debt monetization. The lesson from Japan is that artificial yield caps are currency negative and can spark a devaluation spiral that’s hard to get out of. The Dollar has fallen sharply since last week’s buyback announcement and gold is now up over seven percent (see chart below). Markets know exactly what game is being played and are happy to jump on the debasement trade.
excellent as always. This never works. Ever since Soros and the Pound (Bessent had nothing to do with this; he was getting coffee). The reason shorting a government had not happened before was a lack of imagination. Soros saw the overvaluation and was not intimidated by going up against a government and had fire power and he won. Now there is no lack of imagination problem but people were afraid of going against the USG as they were the global super power. you point out the story of Japan and their economy and their citizens have paid in many ways. Their subsidization of the carry trade has given billions of profit to arbitrage and cratered the Yen. Debasement.
I would like to put out there the negative label of "Bond Vigilantes" is innapropriate. A vigilante is someone(s) who take the dispensing of justice into their own hands without legal sanction. That is not what is going on here. The use of the term here reminds of the term "junk bonds". we coined the phrase "high yield' bonds because they were high yield bonds. They were not junk; they were priced for risk and the risk reward worked out just fine with public high yield at $1.5T and Private Credit, which is sort of the same thing at a similar size. But Marty Lipton, Teddy Forstmann, the investment banks who were losing fees and market share all tried to vilify them and started calling them Junk Bonds. eventually they all joined the party.
so back to the thought. These are not vigilantes; this is the market and they correctly see that the American Empire is self immolating, the debt at $40 T is getting too high, neither party can actually reduce spending or increase taxes and there should therefore be a higher risk premium of USG debt. It is not heresy, treason, vigilantism etc.
Bessent will fail.
He will run out of powder
Let's call them something different
How about Catfish?
The purpose of catfish in an aquarium is to clean up the shit.
Thank you. Let the debasement trade begin!