
Thank you for subscribing to my posts. If you’re not yet a paying supporter, please consider becoming one. That’ll allow you to DM me with questions and comments. Your contribution will help cover the cost of the data I use in my posts, which I fund out of my own pocket. Thanks so much for your support and feedback!
This year is shaping up to be one for the record books. We’ve gone from all-out panic on oil to what now can only be described as fatigue and indifference. Appreciation of the Fed has deteriorated sharply with all the recent talk about a communications and credibility crisis. And then there’s the Yen, where consensus on whether the currency will continue to weaken depends entirely on how effective last week’s intervention is at arresting the trend depreciation that’s been underway for the past two years.
In today’s post, I go through different assets where market sentiment has swung most profoundly versus where it remains in flux. The biggest swing has to be on oil, where the oil bulls - so vocal just a few months ago - have fallen silent, even as the stand-off between the US and Iran over the Strait of Hormuz remains unresolved. The swing in sentiment on the Fed is equally remarkable, though that’s mostly in my opinion about markets struggling to adjust to a world with less forward guidance. Sentiment on the Yen had shifted steadily more bearish - with growing appreciation that it’s artificially low government bond yields that are driving the depreciation trend - but that’s now in flux as markets await just how impactful last week’s intervention turns out to be.
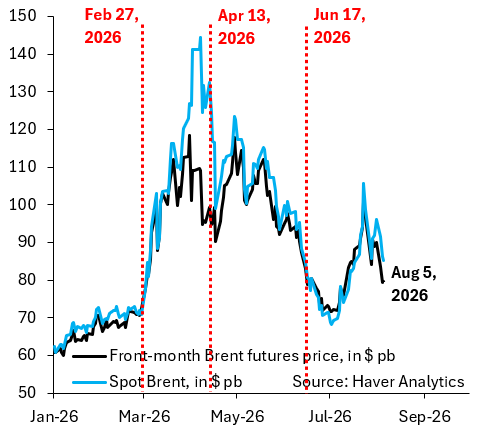
The oil bulls have gone silent: tanker traffic through the Strait of Hormuz is still severely encumbered, but there’s no longer any talk this will spike oil prices in a big way. That’s a remarkable shift from just a few months ago and illustrates just how discredited apocalyptic forecasts like $200 oil have become. One comment I hear frequently is that - even if we go back to all-out war - oil prices won’t spike anywhere near $200 and that’s in line with my view, which is that $125 will be the peak in such a scenario, even with inventories having been run down materially. You can see just how much sentiment has changed in the chart above. The stand-off with Iran is unresolved, yet Brent is around $80 per barrel.
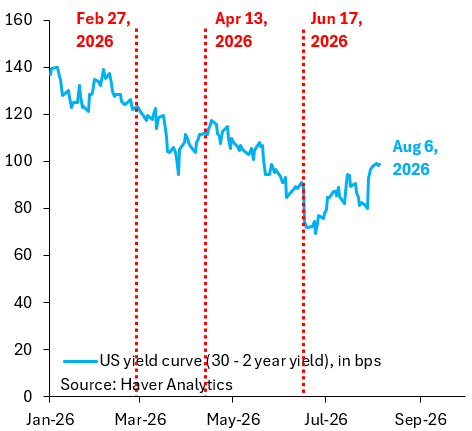
Markets have become very critical of the Fed: I’m not a fan of all the bashing of Kevin Warsh that’s going on for two reasons. First, there’s a long list of previous Fed Chairs who struggled with communication when they first got started. All the talk about Fed credibility seems wildly premature to me. Second, it’s also far from obvious that much of this is being traded. After all, as the chart above shows, the slope of the yield curve has really just retraced the drop that happened the day of the June FOMC meeting. If there was no credibility crisis before June 17, it’s hard to claim there’s one now. Sentiment has swung wildly here, but - to me - much of this is ill-informed. The only thing that’s happening is that markets are learning to trade without as much forward guidance. They still have a long way to go.
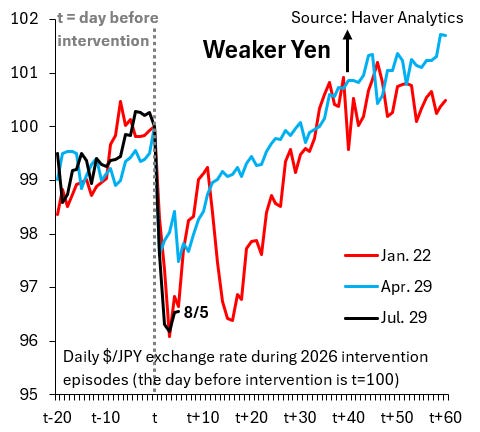
Sentiment on the Yen is in flux: sentiment had been steadily shifting in a bearish direction before last week’s intervention and there was a growing appreciation that the fall in the Yen is about artificially low government bond yields in Japan, which drive capital outflows and Yen depreciation pressure. I’m doubtful that FX intervention can change this, but markets are more open-minded. At this point, everything is a function of how the Yen trades. So far, as the chart above shows and as I argued in yesterday’s post, things look underwhelming. Japan and the US are being extremely aggressive about intervention this time around, yet $/JPY (black line) has moved only as much as in the January rate check episode (red line). I see this as testament to large, ongoing depreciation pressure on the Yen.
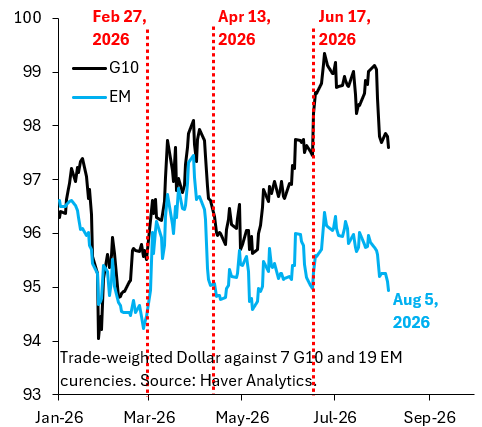
The Dollar bears are back: this year began with consensus overwhelmingly Dollar bearish. That changed after hostilities in the Persian Gulf began, but in my opinion that shift was a mistake. The rise in the Dollar during the early months of the war was entirely due to safe haven inflows into the US as risk aversion spiked. These flows will reverse as soon as the war ends. Markets are gradually coming to the same conclusion, as the chart above shows. The Dollar versus EM has fallen back to its lows, a sign markets are returning to their Dollar down baseline.
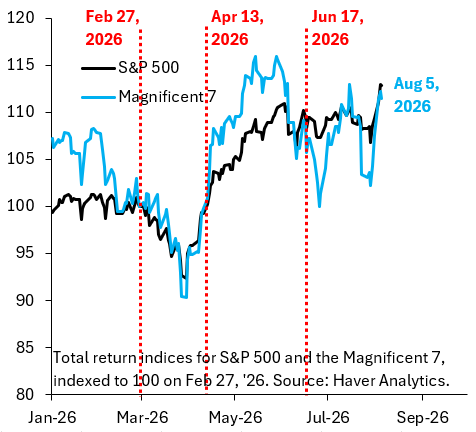
Noise but no direction on AI: the chart above indexes the S&P 500 (black line) and an index comprised of the magnificent seven (blue line) at 100 on Feb. 27, the day before the war began. The latter index is clearly more volatile than the broad market, but there’s no underperformance of the magnificent seven. That says to me there’s nothing idiosyncratic about these stocks - they’re really just following the broader market. That suggests markets don’t actually have a strong view on AI. They’ve been pretty agnostic since the start of 2026.
The Mag 7 chart is the sharpest observation here — if those names aren’t underperforming the broad index despite the AI narrative churn, markets are pricing them as beta, not conviction. That’s a quieter story than the Fed-bashing headlines but probably the more durable one.
The subtler part of the actions around Japan and JPY last week was the implication that interest rate differentials are set to narrow. Pressure on the BoJ is increasing and the pricing for a rate hike in September has increased substantially. Why is this not a variable you focus on in addition to blunt intervention ?