
The Dollar rebounded yesterday. It’s tempting to think this was about Kevin Warsh and that the fall in the Dollar might be over. After all, I’ve argued that the recent drop in the Dollar - much like in April 2025 - was about markets’ dislike of the policy chaos in Washington. An experienced policy maker like Warsh might be a steadying hand and reduce scope for such policy chaos in the future.
Today’s post does three things. First, it lays out why yesterday’s Dollar rebound was only peripherally about Warsh. Second, it explains why the Dollar will continue on its weakening cycle. Third, there’s obviously a huge bubble component to the crazy rally in precious metals. Yesterday’s correction underscored that. However, the structural drivers of the debasement trade run deep, so this correction - like the one in October 2025 - will likely be short-lived.
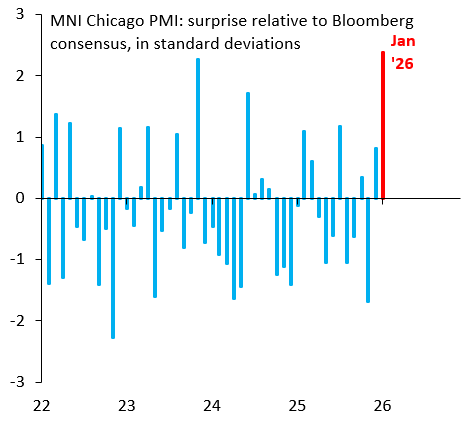
Having spent many years on Goldman’s trading floor, I’ve learned the value of tick-by-tick price action, which is really the only way to get a feel for what’s priced. So here’s what happened yesterday. Trump posted on Truth Social at 6:48 am that Warsh is his nominee for Fed Chair. The Dollar showed no reaction until 10:00 am, whereupon it rose half a percent over the next two hours. It’s not obvious this rise was about Warsh, because - as the chart above shows - the Chicago PMI had a very strong reading at 9:45 am (a 2.4 standard deviation upside surprise versus Bloomberg consensus). As a result, a good chunk of yesterday’s Dollar rally really wasn’t about Warsh. At most, it was about Warsh in conjunction with improving expectations for US growth.
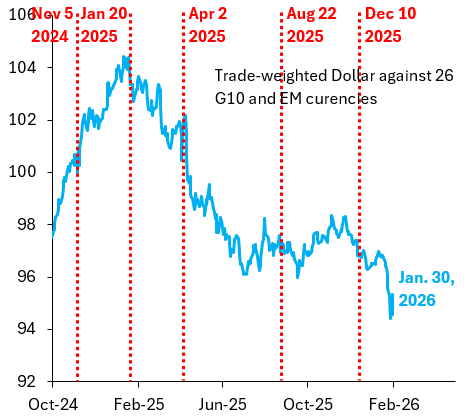
My best guess is that the Dollar would have stayed flat yesterday, had it not been for very strong data. In this context, it’s worth recalling that Trump’s repeated assaults on Fed independence did absolutely nothing to the Dollar. As the chart above shows, the fall in the Dollar over the past year has been concentrated in April 2025 and again this month. These episodes were about markets’ aversion to policy chaos, including the questionable rollout of reciprocal tariffs and the recent escalation over Greenland. If concerns over Fed independence didn’t get priced ahead of yesterday, that’s a further argument - at least in my mind - that yesterday’s rally really wasn’t about Warsh.
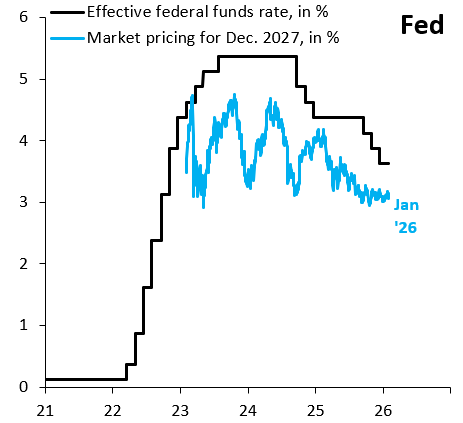
Back in the day, I’d make points like this to the head of currency trading at Goldman and he’d shoot me a look that said: “Nerd!” So let’s focus on the Dollar going forward. Warsh spent the past year campaigning for the job and promised rate cuts as part of that. He thinks the US is in a high productivity, low inflation equilibrium and that Fed policy is therefore too tight. It’d be reasonable, if you believe this, to reset policy as quickly as possible once you start in the job. This boils down to that, in my view, we’ll get much deeper, front-loaded rate cuts than what’s priced, which - as the chart above shows - is only 50 basis points through 2027. I don’t believe the productivity story, but I can see how it might be used to make 100 basis points in cuts in the four meetings (June, July, September, October) ahead of the midterms. That’s one reason why I think the Dollar will keep falling. The other is Trump’s policy chaos, which will continue.
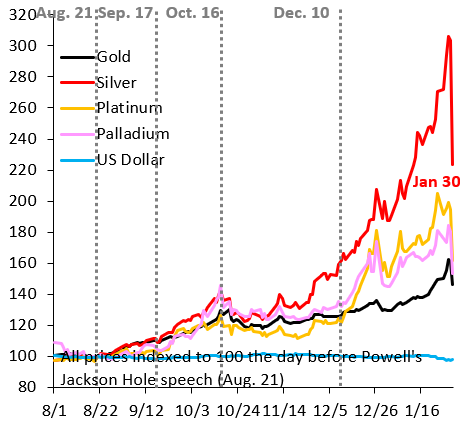
One obvious pushback to my view is yesterday’s massive fall in precious metals. As the chart above shows, silver fell a stunning 26 percent, while gold was down nine. Drops of this size could mean markets had a very hawkish reaction to Warsh, which would argue against Dollar weakness. I think that’d be a reasonable argument to make if precious metals hadn’t been in a speculative frenzy in recent weeks. But they were, so I don’t think there’s much to read into this pullback. This kind of volatility is just what happens in a bubble.
As I’ve argued previously, I don’t think the presence of a bubble in precious metals invalidates the debasement trade, which is about markets seeking safe havens from debt monetization. That’s a much more medium-term driver, which is also getting expressed in rapidly rising long-term government bond yields globally and a rush to safe haven currencies. In my opinion, this means the precious metals frenzy will soon take off again, just like it did after the October pullback. Fiscal policy is just much too reckless in far too many places.
The FT ran a piece noting that he is also purported for increasing more QT: Fed “balance sheet now stands at $6.6tn, following a three-year reversal of QE — dubbed “quantitative tightening” — that the rate-setting Federal Open Market Committee has recently paused amid signs banks were falling short of reserves. Warsh has said he would like to shrink it much further — a move that would raise tensions with rate-setters still scarred by the violent market reaction to their attempts to lower their holdings of government debt in 2019. Warsh in April said successive QE programmes meant politicians found it “considerably easier appropriating money knowing that the government’s financing costs would be subsidised by the central bank”.”
I suspect that the larger story here is still the subordination of the fed to the treasury dept… and this is a sub story of the U.S. economic reorientation towards the next normal as part of U.S. competition with China.
Does Kevin Warsh really have room to manoeuvre — or is he essentially a prisoner of economic reality?