
Thank you for subscribing to my posts. If you’re not yet a paying supporter, please consider becoming one. That’ll allow you to DM me with questions and comments. Your contribution will help cover the cost of the data I use in my posts, which I fund out of my own pocket. Thanks so much for your support and feedback!
For the past two years, pretty much since the 2024 election, there’s been big foreign inflows into US equities. This coincides with all the excitement over AI and is leading to speculation that - since equity flows are typically unhedged - this could be the start of a major strengthening cycle in the Dollar. The fact that the Fed just hiked and may hike more is adding to the case for Dollar strength. Dollar weakness, which seemed like a slam dunk at the start of 2026, has gone out the window for many investors.
Today’s post reviews the evidence on foreign inflows into US equities and whether they’re a reliable predictor for Dollar direction. They aren’t. The easiest way to see that is to think back to all the ups and downs we’ve seen in the Dollar over the past two years when foreign inflows into US equities were strong. If those flows had played a big role, the Dollar would have gone straight up, but it hasn’t. Instead, the Dollar has traded “meat and potatoes” stuff like rate differentials and - since the war began - risk aversion. As far as Fed hikes go, there’s no way the Fed is going to hike as much as markets price, which I laid out in a recent post and Saturday’s live stream. At this point, the Fed is a catalyst for Dollar weakness, not Dollar strength.
I remain in the Dollar down camp. What people forget in my opinion is that - as soon as the war ends - the Dollar will tumble along with oil prices. This isn’t something we need to speculate about. We have hard evidence. Once the war began to de-escalate in April, the Dollar fell sharply alongside oil. Recent Dollar strength is a red herring in my view. Markets have convinced themselves we’re in a big hiking cycle when - in fact - we’re in the age of Dollar debasement. So I’m sticking with my Dollar down call.
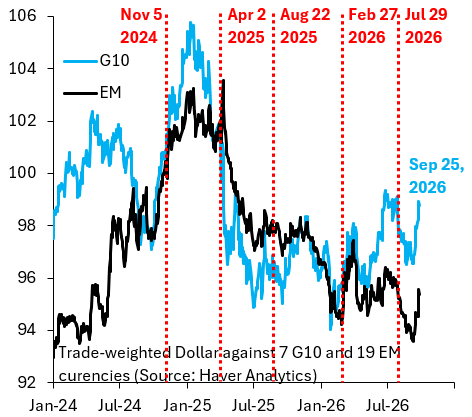
First things first. The blue line in the chart above looks at the Dollar versus the G10, while the black line is the Dollar versus emerging markets (EM). Two things stand out. First, in the two years in which foreign flows into US equities have been strong, the Dollar has gone every which way. Just think back to a year ago when everyone was fretting about loss of US reserve currency status. There’s just no evidence that foreign flows into US stocks have reliably strengthened the Dollar. Second, the hawkish shift by the Fed since Jackson Hole has lifted the Dollar, but this is predicated on markets pricing lots more hikes than I think the Fed can deliver. I therefore look at recent Dollar strength with a large grain of salt.
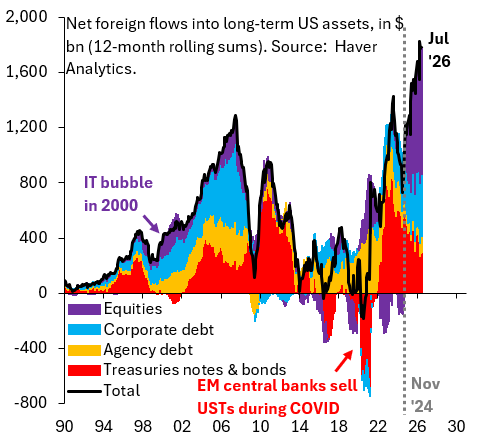
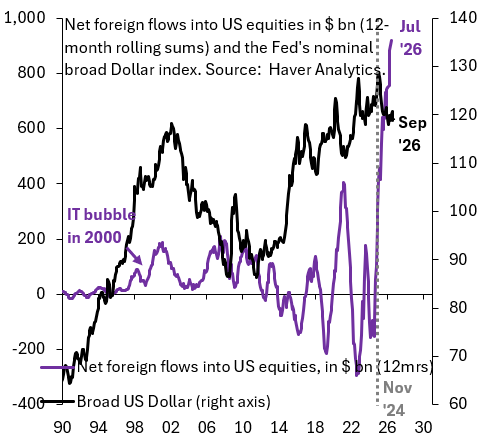
The chart above shows what’s going on with foreign flows. The purple bars are foreign flows into US equities and there’s no doubt these have gone nuts. The recent surge is a bit similar to the IT bubble in the early 2000s, when there were also strong flows into US equities and speculation this would lead to Dollar strength. The black line in the chart below is the broad, trade-weighted Dollar. The purple line is foreign flows into US stocks, so it’s the same series as in the chart above. The point the chart makes clearly - especially in the last two years - is that these flows play essentially no role in the evolution of the Dollar. They’re getting swamped by all the other flows in the balance of payments that are linked to interest rate differentials and safe haven buying or selling. My bottom line is that you want to stick to your guns on Dollar weakness. The AI buildout and associated flows are second-order for the Dollar, which I also showed is true for US Treasury yields in this post.
Net capital inflows are the result of trade deficits - which increased slightly since DJT started the tariff wars. Whether they have an impact on the USD is not so straight forward as many factors play into movements on the margin. But I'm not sure what metric you use to justify a structural USD weakness? To the extent AI and a rise in Oil prices benefit the US more than Europe (relatively insulated from the AI boom and vulnerable to oil prices) or Asia (very vulnerable to oil but hosting many suppliers to AI related CAPEX) and increases the real growth gap (and arguably the real rate gap) of course it is beneficial to the USD. When Oil falls, the reverse is true but AI and growth overall are still there. The argument must be that the fiscal situation in the US is not only worse than in Japan and Europe but also outweighing the growth benefits. But is it really the case? USD down and nominal rates down (which I believe is your related position) is a risky call.
Wow, that Equities image is bonkers.